5 Common Mistakes Homeowners Make: Can I Do a Short Sale After Losing My Job?

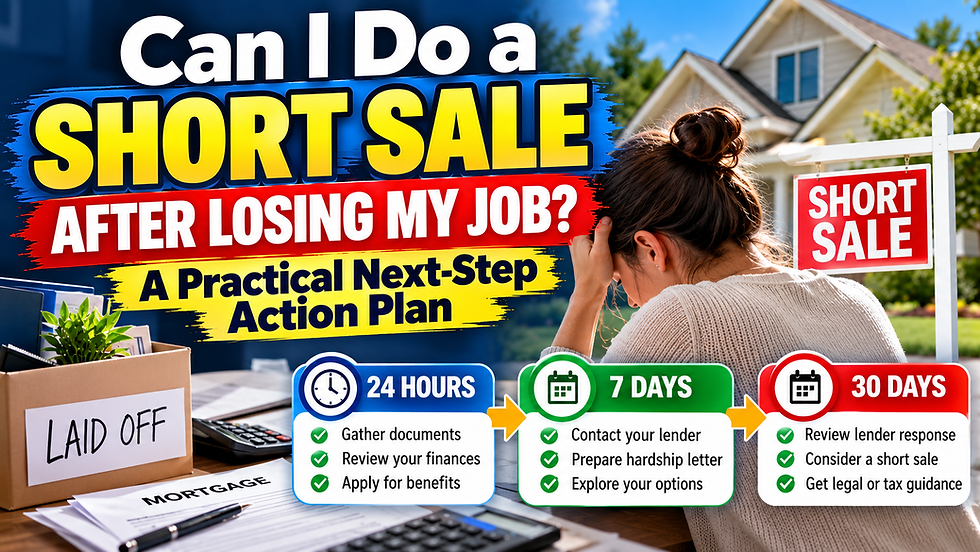
Losing a job can make keeping up with a mortgage difficult, but homeowners can make the situation harder by waiting too long, submitting incomplete information, or assuming a short sale is automatically approved. Job loss can potentially be a financial hardship that supports a short-sale request, but it does not guarantee approval. The mortgage servicer may review your income, expenses, hardship, documentation, property, loan requirements, and other available options. If you are considering a short sale after job loss, understanding the most common mistakes can help you prepare for a more organized lender review.
What Mistakes Should Homeowners Avoid When Dealing With Job Loss and a Short Sale?
The five mistakes to avoid are:
Waiting too long to contact the mortgage servicer
Writing an unclear or incomplete hardship letter
Failing to document the loss of income
Assuming unemployment benefits automatically solve the mortgage problem
Starting a short sale without understanding the lender review process
Each mistake can create delays, confusion, or additional financial pressure. The safer approach is to document your situation, communicate early, and understand your available options before making major decisions.
Mistake #1: Waiting Too Long After Losing Your Job
One of the most common mistakes after a job loss is waiting until mortgage payments are significantly behind before asking for help.
A homeowner may hope to find another job quickly or believe the situation will resolve itself. However, mortgage obligations continue while employment income is reduced or unavailable.
The Consumer Financial Protection Bureau advises homeowners experiencing difficulty with mortgage payments to work with their mortgage servicer or a housing counselor and explains that available assistance depends on the loan and the homeowner's circumstances.
Why This Mistake Happens
Job loss can be stressful, and homeowners may initially focus on finding another job rather than addressing the mortgage.
Some may also worry that contacting the lender will immediately trigger foreclosure activity.
A Safer Alternative
Contact the mortgage servicer as soon as you recognize that your income loss may affect your ability to make payments.
Ask what loss-mitigation options are currently available and what documents are needed for an evaluation.
You can also speak with a HUD-approved housing counselor to understand possible options.
Early communication does not guarantee a particular outcome, but it can give you more time to understand the process.
Mistake #2: Writing a Vague or Incomplete Hardship Letter
A hardship letter can help explain why your financial circumstances changed.
After losing a job, a homeowner might write only:
"I lost my job and cannot pay my mortgage."
That statement may not provide enough context for a lender or servicer reviewing the situation.
Why This Mistake Happens
Homeowners may not know what information to include. Others may write the letter quickly because they are trying to complete a larger loss-mitigation package.
A Safer Alternative
Keep the hardship explanation factual, concise, and consistent with your financial documents.
Depending on what the servicer requests, explain:
When you lost your employment
Whether the employment ended permanently or temporarily
How your income changed
How the income loss affected your ability to make mortgage payments
Whether you receive unemployment benefits
What other income is currently available
Your current financial obligations
What steps you have taken to address the income loss
Why you are asking the servicer to review your available options
Avoid exaggerating or leaving out important information.
The purpose is to give the lender a clear picture of what changed and how that change affects your ability to maintain the mortgage.
Mistake #3: Failing to Document the Income Loss
A verbal explanation of job loss may not be enough.
A lender or servicer may require financial documentation to evaluate your circumstances. Requirements can vary based on the mortgage, servicer, investor, and type of assistance being considered.
Why This Mistake Happens
Homeowners may assume that a termination notice or unemployment approval is all they need.
Others may wait until the servicer requests documents before gathering financial records.
A Safer Alternative
Create a financial document folder as soon as possible.
Depending on your situation, it may include:
Recent mortgage statements
Bank statements
Recent pay stubs
Employment termination documentation
Unemployment benefit documentation
Tax returns
Monthly expense information
Asset information
Hardship letter
Other forms requested by the servicer
Keep copies of everything you submit.
If the servicer asks for additional documents, respond promptly and make sure the information is accurate and consistent.
Federal mortgage-servicing rules address incomplete loss-mitigation applications and the need for servicers to identify missing information or documents. Requirements and timelines can depend on the circumstances of the loan.
Mistake #4: Assuming Unemployment Benefits Automatically Fix the Mortgage Problem
Unemployment benefits can provide temporary income after a job loss, but homeowners should not automatically assume those benefits will make the mortgage affordable.
Your unemployment benefits may be only a portion of your previous income, and they may have a limited duration.
Why This Mistake Happens
Homeowners may think:
"I am receiving unemployment, so I should be able to keep making my mortgage payment."
But the important question is whether your current income and resources are sufficient to cover the mortgage and other necessary expenses.
A Safer Alternative
Create a realistic budget based on your current financial situation.
Compare:
Current income
Unemployment benefits
Savings
Mortgage payment
Property expenses
Utilities
Insurance
Debts
Other necessary monthly expenses
Then determine whether the income reduction appears temporary or whether there is a longer-term affordability problem.
Unemployment benefits may be part of the financial information considered during a mortgage review, but they do not by themselves determine short-sale eligibility.
Mistake #5: Assuming Job Loss Automatically Means the Short Sale Will Be Approved
This is one of the most important mistakes to avoid.
Losing your job can be a hardship, but it does not automatically qualify you for a short sale.
A short sale involves a proposed sale in which the expected proceeds may not fully satisfy the mortgage debt. The lender or mortgage servicer must review the transaction under the requirements applicable to the loan.
Why This Mistake Happens
Homeowners may hear that unemployment is a qualifying hardship and assume that the short sale is therefore guaranteed.
But hardship is only one part of the overall review.
A Safer Alternative
Treat the short sale as an option to evaluate rather than an automatic solution.
Ask your mortgage servicer:
What loss-mitigation options are available?
Does my job loss qualify as a hardship for review?
What documents do you need?
Do you require a hardship letter?
How should unemployment benefits be documented?
Who owns or guarantees my mortgage?
What are the requirements for a short sale?
Are there alternatives I should consider?
What deadlines should I be aware of?
HUD guidance encourages homeowners facing mortgage difficulty to contact their servicer, gather financial documents, and work with a HUD-approved housing counselor.
Some investor guidelines also specifically address temporary and permanent reductions in income when determining available mortgage workout options. For example, Fannie Mae guidance describes different options depending on whether a hardship is temporary or permanent.
How to Prepare for a Short Sale After Job Loss
If losing your job has made your mortgage difficult to maintain, organization can make the next steps easier.
Step 1: Document What Changed
Write down the date your employment ended and how your income changed.
Keep supporting documentation.
Step 2: Calculate Your Current Financial Position
List your current income, unemployment benefits, savings, mortgage payment, debts, and necessary expenses.
Step 3: Contact Your Mortgage Servicer
Ask for the current loss-mitigation options and documentation requirements.
Do not assume that requirements from another homeowner or another mortgage apply to your loan.
Step 4: Prepare Your Hardship Explanation
Explain the income loss clearly and factually.
Make sure the information matches your financial records.
Step 5: Explore All Available Options
A short sale may be one possibility, but other mortgage-assistance options may also exist depending on your circumstances.
Step 6: Keep a Record of Communications
Save letters, emails, forms, document submissions, and notes about conversations with your servicer.
This can help you track requests and deadlines.
How Timing Can Affect a Short Sale After Job Loss
Timing matters because mortgage problems can become more complicated as they progress.
That does not mean every homeowner should immediately pursue a short sale. Instead, the goal is to understand your options early enough to make informed decisions.
If you recently lost your job, consider organizing your documents and contacting your servicer before assuming that you have only one path forward.
If foreclosure proceedings have already begun, deadlines may become especially important. Ask the servicer about applicable dates and seek qualified legal or housing counseling when appropriate.
When Should You Get Professional Help?
A short sale can involve several different areas, including real estate, mortgage servicing, contracts, and potentially legal or tax considerations.
Consider getting appropriate professional guidance if you have questions about:
The legal consequences of a short sale
Potential tax consequences
Deficiency liability
Foreclosure deadlines
The terms of a proposed lender approval
Your specific mortgage requirements
A HUD-approved housing counselor can help explain mortgage-assistance options. An attorney or tax professional may be appropriate for questions requiring legal or tax advice.
Frequently Asked Questions About Short Sale After Job Loss Mistakes
1. Can job loss qualify as a hardship?
Yes. Job loss can create a financial hardship because it can substantially reduce or eliminate income available for mortgage payments. However, hardship does not automatically mean a homeowner qualifies for a short sale.
2. What is the biggest mistake after losing a job and struggling with the mortgage?
Waiting too long to communicate with the mortgage servicer can make the situation more difficult to manage. Homeowners should consider contacting the servicer promptly to understand available options and documentation requirements.
3. Do I need a hardship letter for a short sale after job loss?
You may. Requirements vary by mortgage servicer and loan type. If requested, the hardship letter should accurately explain the job loss, income reduction, financial impact, and current circumstances.
4. Can I receive unemployment benefits and still request a short sale?
Potentially. Unemployment benefits may be considered as part of your current financial circumstances. They do not automatically qualify or disqualify you from a short sale.
5. What documents should I prepare after losing my job?
Start with your mortgage statement, bank statements, income records, employment-loss documentation, unemployment records, tax information, monthly expenses, and any forms requested by your mortgage servicer.
6. Does losing my job guarantee short-sale approval?
No. The lender or servicer must review the circumstances and transaction under the requirements applicable to the mortgage. Job loss can support a hardship explanation but does not guarantee approval.
7. Should I stop making my mortgage payments if I am pursuing a short sale?
Do not assume that pursuing a short sale means you should stop making payments. Ask your mortgage servicer how payments should be handled and consider appropriate professional advice based on your circumstances.
The Bottom Line: Avoid These Short Sale Mistakes After Job Loss
A short sale after job loss may be an option worth discussing when unemployment has created a significant financial hardship. But homeowners should avoid assuming that job loss automatically creates short-sale eligibility.
The most important steps are to act promptly, document the income loss, prepare an accurate hardship explanation, understand your unemployment benefits and current budget, and communicate with your mortgage servicer throughout the review.
Your circumstances, mortgage, investor requirements, property, and available alternatives can all affect the process.
Talk through your hardship and timeline.


Comments