5 Common Mistakes Homeowners Make: Can I Do a Short Sale After Losing My Job?

Losing your job can quickly turn an affordable mortgage into a financial burden. The biggest mistakes homeowners should avoid when considering a short sale after job loss are waiting too long to contact the mortgage servicer, providing incomplete hardship documentation, writing an unclear hardship letter, misunderstanding how unemployment benefits are treated, and assuming a short sale is automatically approved. Job loss can be a financial hardship, but the available options depend on the homeowner’s circumstances, mortgage, property value, servicer requirements, and applicable loan or investor guidelines.
If your income has dropped and you are worried about making your mortgage payments, understanding these short sale after job loss mistakes can help you prepare more effectively and avoid unnecessary delays.
What Mistakes Should Homeowners Avoid After Losing a Job?
Homeowners considering a short sale after job loss should avoid five common mistakes:
Waiting too long to contact the mortgage servicer.
Submitting an incomplete or poorly organized hardship package.
Writing a hardship letter that does not clearly explain the income loss.
Assuming unemployment benefits are treated the same as regular employment income.
Assuming job loss automatically qualifies the homeowner for a short sale.
Each mistake can create confusion, delays, or missed opportunities to understand available mortgage options.
Mistake #1: Waiting Too Long to Contact the Mortgage Servicer
One of the most common mistakes after losing a job is waiting until mortgage payments are significantly behind before asking for help.
A homeowner may think, “I will find another job first,” or “I only need a few weeks to catch up.” Sometimes the financial situation improves. But if the income loss continues, delaying the conversation can leave less time to review available options.
The Consumer Financial Protection Bureau recommends contacting the mortgage servicer as soon as you know you may have difficulty making your mortgage payment. HUD also advises homeowners experiencing financial problems to contact their lender or servicer and explore available foreclosure-prevention options.
Why This Mistake Happens
Job loss can be stressful. Homeowners may feel embarrassed, overwhelmed, or hopeful that another job will appear quickly.
Another common assumption is that contacting the lender means foreclosure will immediately begin. In reality, contacting the servicer is an important first step in understanding available loss-mitigation options.
A Safer Alternative
Contact your mortgage servicer early.
Explain that you experienced an income loss and ask:
What assistance options are available?
Is a short sale an option for this loan?
What documents are required?
Are there deadlines I need to know about?
What happens if I cannot make the next payment?
Are there options other than a short sale?
Do not assume a short sale is your only option. Depending on the circumstances, other loss-mitigation options may be available.
Mistake #2: Submitting Incomplete Financial Documentation
Another major short sale after job loss mistake is submitting an incomplete financial package.
A short-sale review can require detailed information about your income, expenses, assets, mortgage, hardship, and property. Requirements can vary depending on the loan and investor.
For example, Fannie Mae's current servicing guidance describes documentation and evaluation requirements for short sales, including borrower eligibility, property valuation, financial information, and transaction review.
Why This Mistake Happens
Homeowners may send only the documents they think are important.
For example, someone who has just lost a job may submit a termination letter but forget to provide bank statements, benefit documentation, expense information, mortgage statements, or other requested records.
The result can be requests for additional documents and potentially more time spent completing the review.
A Safer Alternative
Create a short sale after job loss document checklist before submitting your package.
Depending on what your servicer requests, this may include:
Mortgage statement
Bank statements
Recent pay stubs, if applicable
Employment termination documentation
Unemployment benefit documentation
Severance information
Tax returns
Monthly expense information
Asset information
Hardship letter
Property information
Information about other liens
Any forms supplied by the mortgage servicer
Keep copies of everything you submit.
Do not send unnecessary documents simply to make the package larger. Follow the specific checklist provided by your mortgage servicer.
Mistake #3: Writing a Hardship Letter That Is Too Vague
A hardship letter is another area where homeowners can lose time by providing an explanation that is too short, unclear, or unsupported.
A statement such as:
“I lost my job and cannot afford my mortgage anymore.”
may explain the basic problem, but it does not provide much detail.
Why This Mistake Happens
Homeowners often assume the lender already knows what happened.
The servicer may know that a payment was missed, but that does not necessarily provide the complete financial story behind the missed payment.
A clear hardship explanation connects the event to the change in the homeowner's financial circumstances.
A Safer Alternative
A hardship letter should generally explain:
What happened:When did you lose your job?
How it changed your finances:How did your income change?
What is happening now:Are you receiving unemployment benefits, using savings, working temporary employment, or looking for another job?
Why the mortgage is difficult to maintain:How has the income reduction affected your ability to pay the mortgage and other essential expenses?
What are you requesting:Are you asking the servicer to review available loss-mitigation options, including whether a short sale may be appropriate?
Keep the letter factual and consistent with the documents you submit.
A hardship letter should not exaggerate your circumstances or include information that cannot be supported.
Mistake #4: Assuming Unemployment Benefits Are Treated Like Regular Income
After losing a job, unemployment benefits may become an important source of temporary income.
One mistake homeowners make is assuming that unemployment benefits will automatically be treated exactly like wages during a short-sale review.
That is not necessarily the case.
For example, Fannie Mae's published servicing guidance states that unemployment insurance benefits and certain temporary employment-related sources are not included as monthly gross income for its short-sale housing expense-to-income calculation.
This is an important distinction because loan programs and investor requirements can differ.
Why This Mistake Happens
Homeowners naturally think:
“I receive $X per month, so that must be my monthly income for the review.”
But mortgage servicing calculations can use specific definitions and rules.
A Safer Alternative
Document your unemployment benefits accurately, but ask the servicer how they will be treated under your specific loan requirements.
Keep documentation showing:
Benefit approval
Benefit amount
Payment dates
Remaining benefit period, if applicable
Other current income
Any new employment income
Do not hide unemployment benefits or assume they automatically determine whether you qualify.
The goal is to give the servicer an accurate picture of your current financial situation.
Mistake #5: Assuming Job Loss Automatically Qualifies You for a Short Sale
Job loss can be a significant financial hardship, but job loss by itself does not guarantee short-sale eligibility or approval.
A short sale generally involves selling a property for less than the amount owed on the mortgage, with approval from the mortgage servicer or applicable mortgage holders.
The servicer may consider multiple factors.
These can include:
The borrower's financial hardship
Current income
Expenses
Assets
Mortgage balance
Property value
Proposed sale price
Loan requirements
Investor requirements
Other liens on the property
Why This Mistake Happens
Homeowners sometimes hear that “job loss qualifies you for a short sale” and assume the process is automatic.
It isn't.
A hardship may be one part of the review, while the property and loan circumstances can also matter.
A Safer Alternative
Treat job loss as the starting point for a financial review, not an automatic approval.
Ask the servicer:
Does my loan permit a short sale?
What hardship documentation is required?
How will my current income be evaluated?
How will unemployment benefits be treated?
What property valuation is required?
What happens to any remaining mortgage balance?
Are there other options I should consider?
For example, the CFPB explains that homeowners should understand the terms of a short sale, including whether a deficiency could remain and whether the servicer will waive it.
Why Timing Matters After Losing Your Job
Timing is a critical part of handling mortgage difficulty after an income loss.
You do not necessarily need to wait until you are seriously behind on payments before contacting your servicer.
HUD specifically advises homeowners who have experienced a loss of job or another financial change that makes mortgage payments difficult to contact a lender or HUD-approved housing counselor.
Mortgage and foreclosure timelines can vary depending on the loan, servicer, and applicable law. Therefore, homeowners should obtain the actual deadlines that apply to their situation rather than relying on a general internet timeline.
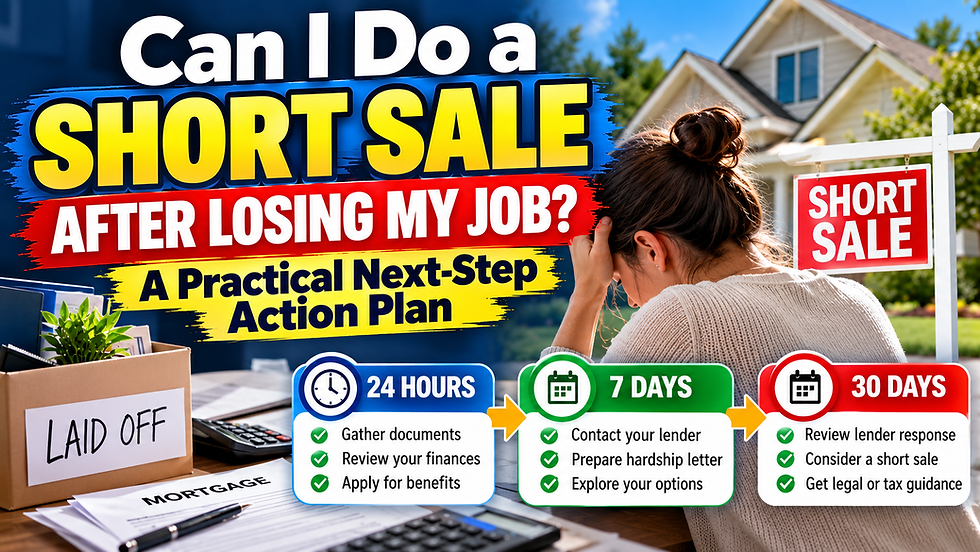
A Simple Timeline to Follow
Today:
Review your mortgage statement.
Identify your mortgage servicer.
Calculate your current income.
List your essential expenses.
Gather job-loss documentation.
Check your unemployment benefit status.
Within the next few days:
Contact the mortgage servicer.
Ask about available loss-mitigation options.
Request the appropriate documentation checklist.
Prepare your hardship explanation.
Gather bank and financial records.
Before making a final decision:
Understand the short-sale process.
Review potential deficiency consequences.
Ask how other liens will be handled.
Ask about possible tax consequences.
Consider speaking with a HUD-approved housing counselor.
HUD-approved housing counselors can provide independent assistance with mortgage delinquency, foreclosure prevention, and related housing issues.
What Should Homeowners Do Instead of Making These Mistakes?
The safer approach is to focus on documentation, communication, and timing.
Start by documenting the job loss.
Then create a clear financial snapshot showing:
Income → Benefits → Expenses → Assets → Mortgage → Property Value
This information can help you have a more productive conversation with your mortgage servicer.
Remember that a short sale is only one potential option. Depending on your situation, your servicer may discuss other loss-mitigation or home-retention options. For example, FHA's current loss-mitigation guidance includes both home-retention options and, for eligible borrowers who cannot retain the property, a pre-foreclosure sale option.
Frequently Asked Questions About Short Sale After Job Loss Mistakes
1. Can losing my job qualify as a mortgage hardship?
Yes. Job loss can create a financial hardship that affects your ability to make mortgage payments. However, experiencing a hardship does not automatically qualify you for a particular loss-mitigation option. Your servicer will evaluate your circumstances and applicable requirements.
2. What is the biggest mistake after losing a job and struggling with a mortgage?
One major mistake is waiting too long to contact the mortgage servicer. CFPB recommends contacting the servicer as soon as you know you may have difficulty making your mortgage payment.
3. Should unemployment benefits be included in my financial documentation?
You should accurately disclose and document your current financial circumstances, including applicable benefits. However, how unemployment benefits are treated in a mortgage review can depend on the specific loan and investor requirements. Fannie Mae, for example, has specific rules regarding unemployment benefits in its short-sale calculations.
4. What documents should I prepare for a short sale after job loss?
The exact requirements vary, but homeowners may be asked for financial statements, mortgage information, income or benefit documentation, expense information, asset information, hardship documentation, and other forms required by the servicer.
5. Does job loss automatically qualify me for a short sale?
No. Job loss can be a hardship, but short-sale eligibility depends on the circumstances and requirements applicable to the mortgage. The servicer may also consider the property's value, mortgage balance, proposed transaction, and other factors.
6. Do I need to wait until I miss a mortgage payment?
You should not assume that you need to wait. CFPB recommends contacting your servicer as soon as you know you may have difficulty making payments.
7. Can a housing counselor help me understand my options?
Yes. HUD-approved housing counselors can provide independent assistance with mortgage delinquency, foreclosure prevention, budgeting, and housing-related financial issues.
Final Takeaway: Avoid These Short Sale After Job Loss Mistakes
A job loss can change your ability to afford your mortgage quickly. The five mistakes to avoid are waiting too long to communicate with your servicer, submitting incomplete documentation, writing an unclear hardship letter, misunderstanding unemployment benefits, and assuming job loss automatically qualifies you for a short sale.
Instead, document what happened, organize your financial records, communicate with your mortgage servicer early, and ask specific questions about the options available for your loan.
A short sale may be one option, but it is not automatically the right or available solution for every homeowner.
Talk Through Your Hardship and Timeline
If you have lost your job and are concerned about your mortgage, talk through your hardship and timeline before making assumptions about what happens next.
Understanding your income loss, documentation, deadlines, property value, and lender requirements can help you prepare for a more informed conversation about your available options.
This article is for general educational purposes only and is not legal, tax, financial, or mortgage-servicing advice. Short-sale requirements and consequences vary by loan, investor, mortgage servicer, property, and applicable law. No outcome is guaranteed. Consider speaking with your mortgage servicer, a HUD-approved housing counselor, and qualified legal or tax professionals when appropriate.


Comments