Can I Do a Short Sale After Losing My Job?
Losing your job can create a serious financial hardship, especially when you are struggling to keep up with your mortgage. Yes, job loss can potentially qualify as a financial hardship for a short sale, but it does not automatically mean a lender will approve one. The lender or mortgage servicer generally reviews your financial situation, income, expenses, mortgage balance, property value, documentation, and available alternatives. If your income has dropped and you can no longer reasonably afford the mortgage, it may be worth discussing a short sale along with other loss-mitigation options.
Can Job Loss Qualify as a Hardship?
Yes. Job loss can be a qualifying hardship in some short-sale situations.
A hardship is generally a significant financial or personal circumstance that affects your ability to maintain your mortgage obligation. A sudden loss of employment can reduce or eliminate the income you were using to make mortgage payments.
HUD guidance specifically recognizes unemployment and loss of employment as circumstances that can affect a borrower's ability to make mortgage payments.
However, there is an important distinction:
Having lost your job does not automatically mean you qualify for a short sale.
Your mortgage servicer may review whether the hardship has created a financial situation that makes keeping the property difficult or unsustainable. The servicer may also consider whether another option, such as forbearance, repayment assistance, or a loan modification, could address the problem.
A short sale is one possible loss-mitigation option, not an automatic result of unemployment.
How Job Loss Can Affect Your Ability to Pay the Mortgage
The financial impact of losing a job can happen quickly.
Your regular paycheck may stop, while your mortgage payment, property taxes, insurance, utilities, and other expenses continue.
You may have:
Lost your primary source of income
Experienced a significant reduction in household income
Used savings to make mortgage payments
Fallen behind on payments
Started receiving unemployment benefits
Taken temporary or part-time work
Increased your credit-card or other debt to cover expenses
Determined that your current mortgage payment is no longer sustainable
These details can help explain the financial circumstances behind your request for assistance.
The Consumer Financial Protection Bureau advises homeowners who are having trouble paying their mortgage to contact their servicer promptly and provide the financial information required for a loss-mitigation review.
What Is a Hardship Letter for a Short Sale?
A hardship letter is a written explanation of the circumstances that caused your financial difficulty and why you are seeking mortgage assistance.
If you are pursuing a short sale after job loss, your hardship letter should focus on facts rather than emotional language.
You may explain:
When you lost your job
Whether the job loss was temporary or permanent
How your income changed
How the income loss affected your ability to make mortgage payments
Whether you are receiving unemployment benefits
What steps you have taken to find new employment
Your current monthly income and expenses
Why keeping the property has become difficult
Why you are asking the lender to review your available options
Keep the information accurate and consistent with your supporting documentation.
The lender may have its own forms, requirements, or preferred format, so ask the mortgage servicer what documentation is required before submitting your package.
What Documents May Be Needed After a Job Loss?
When a lender reviews a hardship or loss-mitigation request, documentation can be an important part of the process.
Depending on the servicer, loan type, and circumstances, you may be asked for documents such as:
Recent pay stubs, if you still have employment income
Proof of termination or job loss
Unemployment benefit documentation
Bank statements
Recent tax returns
Mortgage statements
Monthly expense information
Asset information
A hardship letter
Employment-search documentation
Other financial forms requested by the servicer
Requirements can vary, so do not assume that one checklist applies to every mortgage.
For example, Fannie Mae's published documentation guidance identifies unemployment benefits as an income type that may require supporting documentation when applicable.
The goal is to give the lender a clear picture of your current financial circumstances.
Can I Get Unemployment Benefits and Still Pursue a Short Sale?
Potentially, yes.
Receiving unemployment benefits does not by itself determine whether a short sale will be approved. Instead, unemployment benefits may be considered part of your current financial picture.
Your servicer may want documentation showing:
The amount of your benefits
When the benefits began
How long they are expected to continue
Other income you currently receive
Your current expenses
Your mortgage payment
Your available assets
HUD materials addressing homeowners affected by job loss have also identified unemployment assistance and mortgage assistance as potential resources to investigate.
Because unemployment benefits and mortgage-assistance programs can change, verify current program requirements with the appropriate agency and your mortgage servicer.
When Should You Start the Short-Sale Conversation?
Do not wait until the situation becomes an emergency if you already know your income has changed significantly.
If you recently lost your job, you can begin gathering your financial information and contacting your mortgage servicer to understand your available options.
The Consumer Financial Protection Bureau recommends contacting your servicer when you are having difficulty paying your mortgage and applying promptly for available assistance.
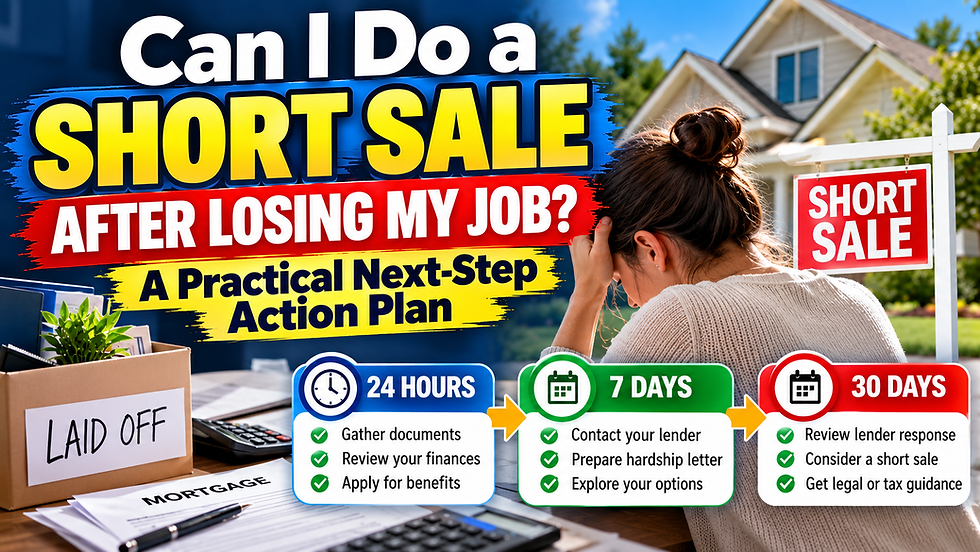
A practical timeline may look like this:
First 24–48 Hours
Gather your basic financial records.
Start a folder containing:
Mortgage statement
Bank statements
Recent income records
Unemployment documentation
Job-loss documentation
Monthly expenses
Property information
Also write down the date your employment ended and when you expect your current savings or other income sources to become insufficient.
Within the First Week
Contact your mortgage servicer.
Ask:
What loss-mitigation options are available?
What documents are required?
Does the servicer need a hardship letter?
What happens if I cannot make my next payment?
Can my loan be reviewed for a short sale?
Are there alternatives I should consider first?
You can also consider speaking with a HUD-approved housing counselor. HUD recommends homeowners experiencing mortgage difficulty seek help early and gather their financial documents.
Over the Next 30 Days
Keep your documentation current.
If you find new employment, receive unemployment benefits, experience another income change, or your financial circumstances change, update the appropriate parties.
If a short sale becomes part of your plan, additional property, listing, offer, and lender-review steps may follow.
What Happens During a Lender Review?
A short sale generally involves the lender or mortgage servicer reviewing a proposed transaction in which the expected sale proceeds are insufficient to fully satisfy the mortgage debt.
The review may consider the homeowner's financial hardship, the property's value, the proposed purchase offer, available documentation, and the circumstances surrounding the request.
The lender ultimately determines whether the proposed transaction meets its requirements.
That means there is no automatic approval simply because you lost your job.
The strongest approach is to provide complete, accurate, and timely information and respond to requests from the servicer as quickly as possible.
Does Job Loss Automatically Mean a Short Sale Is the Best Option?
No.
Job loss may create a hardship, but homeowners can have several possible options.
Depending on the loan and circumstances, alternatives can include:
Forbearance
Loan modification
Repayment arrangements
Other loss-mitigation programs
Selling the property normally
Short sale
Other foreclosure alternatives
The CFPB explains that loss-mitigation options can include temporary payment relief, loan modifications, and short sales or other alternatives to foreclosure.
The appropriate option depends on your individual financial situation, mortgage, property value, loan owner or investor requirements, and the programs currently available.
What Should I Do If I Cannot Make My Next Mortgage Payment?
If you have recently lost your job and believe you may not be able to make your next payment, communicate with your mortgage servicer as soon as possible.
Do not assume that missing payments without contacting the servicer will automatically create a short-sale opportunity.
Instead:
1. Document the job loss.Keep termination notices, unemployment records, and other proof of the income change.
2. Review your finances.Determine your current income, available savings, debts, and monthly expenses.
3. Contact your servicer.Ask about current loss-mitigation options and documentation requirements.
4. Consider housing counseling.HUD-approved housing counselors can help homeowners understand available mortgage-assistance options.
5. Explore the short-sale option if appropriate.If keeping the property is no longer financially realistic, ask whether a short sale review may be appropriate.
6. Get professional advice when necessary.A real-estate professional, housing counselor, attorney, or tax professional may address different parts of the situation. Legal and tax consequences can vary based on individual circumstances.
Frequently Asked Questions About a Short Sale After Job Loss
1. Can job loss qualify as a hardship?
Yes. Job loss can be a financial hardship because losing employment can reduce or eliminate the income available to make mortgage payments. However, hardship alone does not guarantee short-sale approval. The lender or servicer reviews the complete financial situation.
2. Can I request a short sale if I am receiving unemployment benefits?
Potentially. Unemployment benefits can be part of your current financial picture. You may need to provide documentation showing the amount and duration of those benefits.
3. Do I need a hardship letter after losing my job?
You may be asked to provide a hardship letter or another written explanation of your circumstances. Requirements vary by servicer and loan type, so ask what forms and documentation are required.
4. Should I wait until I miss a mortgage payment?
Not necessarily. If you already know that your income loss is affecting your ability to make the mortgage payment, contacting the servicer promptly can help you understand available options before the situation becomes more difficult.
5. Does losing my job guarantee that my short sale will be approved?
No. Job loss can support a hardship explanation, but approval depends on the lender or servicer's review and the requirements applicable to the mortgage.
6. What documents should I gather after losing my job?
Start with your mortgage statement, bank statements, recent income records, unemployment documentation, job-loss documentation, monthly expenses, tax information, and any hardship forms requested by your servicer.
7. Should I talk to a professional before pursuing a short sale?
It can be helpful. A housing counselor can help explain mortgage-assistance options, while a qualified real-estate professional can discuss the property-sale process. An attorney or tax professional may be appropriate when you need advice about legal or tax consequences.
The Bottom Line
A short sale after job loss may be worth exploring when unemployment has created a financial hardship and maintaining the mortgage has become difficult. Job loss can be a legitimate hardship circumstance, but it does not automatically qualify a homeowner for a short sale.
The key is to act early, document the change in income, communicate with your mortgage servicer, understand your available alternatives, and provide accurate financial information for review.
If losing your job has changed what you can realistically afford, the next step is to understand your options based on your specific circumstances.
Talk through your hardship and timeline.


Comments