Can I Do a Short Sale After Losing My Job: Documents and Information to Prepare
Yes, job loss can potentially support a short-sale request when it creates a financial hardship, but it does not automatically qualify a homeowner for a short sale. If you are considering a short sale after losing your job, prepare your income records, unemployment documentation, mortgage information, hardship explanation, important dates, and questions for your mortgage servicer. HUD guidance recommends gathering financial documents and contacting the mortgage servicer or a HUD-approved housing counselor as soon as possible when mortgage payments become difficult.
What Should a Homeowner Prepare Before Taking the Next Step?
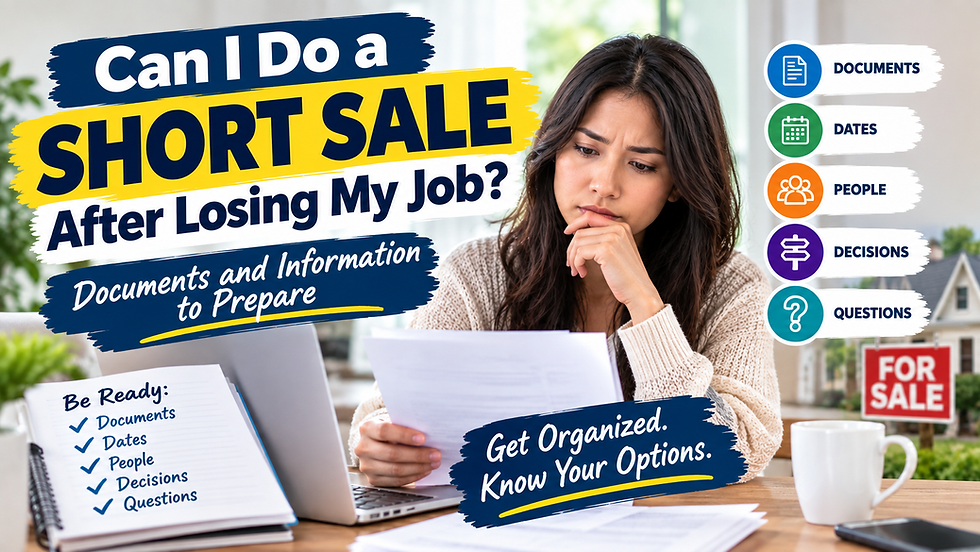
A homeowner considering a short sale after job loss checklist should prepare five categories of information:
Documents — financial and mortgage records
Dates — when the job loss and financial hardship occurred
People — mortgage servicer, housing counselor, real-estate professionals, and other appropriate advisors
Decisions — what options you are considering
Questions — what you need to understand before moving forward
Having this information organized can make conversations with your mortgage servicer more productive and help you understand what additional documentation may be required.
Requirements vary by mortgage servicer, loan type, investor, and individual circumstances, so this checklist should be treated as a preparation guide rather than a guarantee of eligibility or approval.
Short Sale After Job Loss Checklist: Documents to Gather
Start by creating one folder—digital or physical—for your mortgage and financial records.
HUD housing-counseling materials identify several types of financial documentation that may be requested during a mortgage-assistance review, including mortgage statements, income documentation, bank statements, tax returns, information about other debts and assets, and unemployment documentation when applicable.
1. Mortgage Documents
Gather:
Most recent mortgage statement
Loan account information
Information about any second mortgage or other lien
Recent correspondence from your mortgage servicer
Notices concerning missed or upcoming payments
Any previous loss-mitigation paperwork
Keep letters and notices from your servicer in the same folder.
2. Employment and Income Documents
Because the central issue is often the loss or reduction of income, document what changed.
Consider gathering:
Recent pay stubs
Employment termination or separation documentation
Employer correspondence concerning the end of employment
Records showing your previous income
Documentation of any current employment
Documentation of other sources of income
Recent tax returns
If you have started another job at a lower income, include the new income information as well.
3. Unemployment Benefit Documentation
If you receive unemployment benefits, keep documentation showing:
Benefit amount
Start date
Expected duration, if available
Benefit statements
Eligibility or approval notices
Other correspondence related to the benefits
HUD materials specifically identify an unemployment insurance letter as a document that may be requested when applicable.
4. Bank and Asset Information
Your servicer may need information about your current financial resources.
Depending on the requirements, prepare:
Recent bank statements
Savings account information
Investment or retirement account information, if requested
Other asset information
Credit-card balances
Monthly debt obligations
Do not leave out assets or income simply because you believe they may hurt your request. Provide complete and accurate information when it is requested.
Prepare a Clear Hardship Explanation
A hardship letter or written explanation may be part of the mortgage-assistance process.
Your explanation should clearly describe what happened and how the job loss affected your ability to maintain the mortgage.
Consider documenting:
The date you lost your job
Your position or employment status before the job loss
The change in your income
When you first noticed the mortgage becoming difficult to afford
Whether you are receiving unemployment benefits
Whether you have found new employment
Your current income
Your major monthly expenses
Whether you expect the hardship to be temporary or longer-term
Why you are requesting a review of available options
HUD training materials state that a written explanation describing circumstances such as job loss or reduced income may be helpful, although specific requirements vary by servicer and program.
Keep Your Hardship Letter Factual
Avoid making the letter unnecessarily complicated.
For example, explain:
What happened → when it happened → how income changed → how that affected the mortgage → what you are requesting.
Make sure your explanation matches your financial documents.
Mortgage-assistance forms may require borrowers to certify that submitted information is truthful and may allow the servicer to request additional supporting documentation.
Create a Timeline of Important Dates
Timing can matter when dealing with mortgage difficulties.
Create a simple timeline containing:
Date | What Happened |
______ | Employment ended |
______ | Income changed |
______ | Unemployment benefits began |
______ | First payment affected |
______ | Contacted mortgage servicer |
______ | Documents submitted |
______ | Additional documents requested |
______ | Follow-up with servicer |
______ | Important payment or foreclosure-related deadline |
Also save copies of emails, letters, submission confirmations, and notes from telephone calls.
A timeline can help you avoid forgetting important deadlines or losing track of which documents were submitted.
Identify the People Who Can Help
A short sale and mortgage hardship can involve several different professionals.
Mortgage Servicer
Your mortgage servicer is an important first contact because it can explain current loss-mitigation requirements and tell you what documentation is needed for your loan.
Ask who is responsible for handling your loss-mitigation or short-sale review.
HUD-Approved Housing Counselor
HUD recommends homeowners experiencing mortgage difficulty contact a HUD-approved housing counselor. Housing counselors can help homeowners understand available mortgage-assistance options and organize their financial information.
Real-Estate Professional
A qualified real-estate professional can help explain the property-sale side of a potential short sale, including preparing the property for market and handling an offer if the process moves forward.
Attorney or Tax Professional
Consider professional legal or tax advice when you have questions about matters such as deficiency liability, contracts, foreclosure deadlines, or possible tax consequences.
These professionals address different parts of the process, so one person may not be able to answer every question.
Decide What You Need to Understand Before Moving Forward
Do not assume that a short sale is automatically the only option after a job loss.
Depending on the mortgage and circumstances, available loss-mitigation options can differ. HUD explains that mortgage servicers and investors may have different programs and eligibility requirements, and that homeowners should work with their servicer or housing counselor to understand their options.
Before moving forward, consider these questions:
Can I realistically afford the mortgage with my current income?
Is my income loss temporary or potentially long-term?
Am I receiving unemployment benefits?
Do I have savings available?
Are there other sources of income?
Have I contacted my mortgage servicer?
What loss-mitigation options are available?
Is a short sale one of those options?
What documents does my servicer require?
Are there important deadlines I need to know about?
The answers can help you organize your next conversation.
Questions to Ask Your Mortgage Servicer
When you contact your servicer, consider keeping this list nearby.
Ask About Your Hardship
Does job loss qualify as a hardship for purposes of a loss-mitigation review?
What information do you need to document my income loss?
Do you require a hardship letter or specific form?
Ask About Documentation
What documents are required?
How recent must my financial statements be?
Do you need unemployment benefit documentation?
Are additional documents required from other borrowers?
Ask About Timing
When should I submit my application?
Are there deadlines associated with my account?
How should I respond if additional documents are requested?
Who should I contact if I have questions about my application?
Ask About Options
What loss-mitigation options are available?
Is a short sale an option for my loan?
Are there alternatives I should consider?
What happens while my request is being reviewed?
Write down the answers and keep them with your mortgage records.
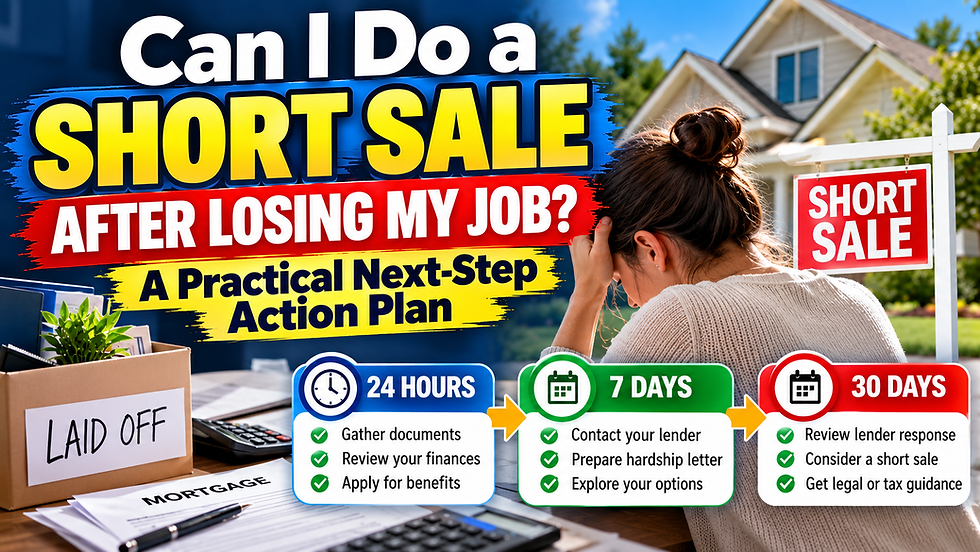
Your 24-Hour Preparation Checklist
If you recently lost your job and are worried about your mortgage, start with these steps.
Today:
☐ Locate your latest mortgage statement
☐ Write down the date your employment ended
☐ Gather termination or employment documentation
☐ Gather unemployment benefit records
☐ Download recent bank statements
☐ Calculate your current monthly income
☐ List your necessary monthly expenses
☐ Start a hardship timeline
☐ Create a folder for mortgage documents
☐ Identify your mortgage servicer's contact information
You do not need to have every answer before contacting your servicer.
The purpose of the first step is to understand what information is required and what options may be available.
Your 7-Day Preparation Checklist
During the next week, focus on completing the financial picture.
☐ Gather recent income records
☐ Gather tax documents if requested
☐ Organize mortgage statements
☐ Document unemployment benefits
☐ List debts and monthly payments
☐ Document savings and other assets
☐ Draft your hardship explanation
☐ Contact your mortgage servicer
☐ Ask about available loss-mitigation options
☐ Consider contacting a HUD-approved housing counselor
☐ Record important deadlines
☐ Save copies of every document submitted
HUD specifically advises homeowners to get help early and gather financial documents when they are having difficulty making mortgage payments.
What Not to Assume About a Short Sale After Job Loss
Preparing a checklist is useful, but there are several things homeowners should not assume.
Job loss does not automatically mean short-sale approval.
Receiving unemployment benefits does not automatically determine eligibility.
Submitting documents does not guarantee a specific outcome.
A hardship letter does not replace the lender's review.
Another homeowner's short-sale process may not apply to your mortgage.
Your mortgage servicer, loan owner or investor, financial circumstances, property, and applicable requirements can all affect the process.
Frequently Asked Questions About a Short Sale After Job Loss Checklist
1. Can I do a short sale after losing my job?
Potentially. Job loss can create a financial hardship that may be considered during a mortgage-assistance or short-sale review. However, losing a job does not automatically qualify a homeowner for a short sale.
2. What should a homeowner prepare before taking the next step?
Prepare mortgage records, income and unemployment documentation, bank statements, financial information, a timeline of the hardship, a clear hardship explanation, important dates, and questions for your mortgage servicer.
3. Do I need a hardship letter after losing my job?
You may. Requirements differ by servicer and loan type. If one is requested, explain the job loss, income reduction, financial impact, and current circumstances accurately and consistently with your documentation.
4. Should unemployment benefits be included in my short-sale documents?
If applicable and requested, yes. Unemployment benefits are part of your current financial picture, and HUD materials identify unemployment documentation as a document that may be requested during a mortgage-assistance review.
5. When should I contact my mortgage servicer after losing my job?
Consider contacting the servicer as soon as you recognize that the income loss may affect your ability to make your mortgage payments. HUD recommends seeking help as soon as possible when experiencing mortgage difficulty.
6. What if I do not have all of my documents yet?
Contact your servicer and ask what is required and what can be submitted first. Do not guess about missing requirements. Servicers may request additional information during the review.
7. Does preparing a short-sale checklist mean I should pursue a short sale?
Not necessarily. The checklist is intended to help you prepare for a conversation and review of your options. A short sale is one possible option, and the appropriate path depends on your circumstances and applicable mortgage requirements.
The Bottom Line
A short sale after job loss checklist can help you organize the information needed before discussing your situation with your mortgage servicer.
Start with five things: documents, dates, people, decisions, and questions.
Document when your job ended, how your income changed, whether you receive unemployment benefits, what you currently owe, and what you can realistically afford. Gather your mortgage and financial records, prepare a factual hardship explanation, and keep track of every communication and deadline.
Most importantly, do not assume that job loss automatically means a short sale will be approved. Use the preparation process to understand the options available for your specific mortgage and financial circumstances.
Talk through your hardship and timeline.


Comments