Can I Do a Short Sale After Losing My Job: Documents and Information to Prepare
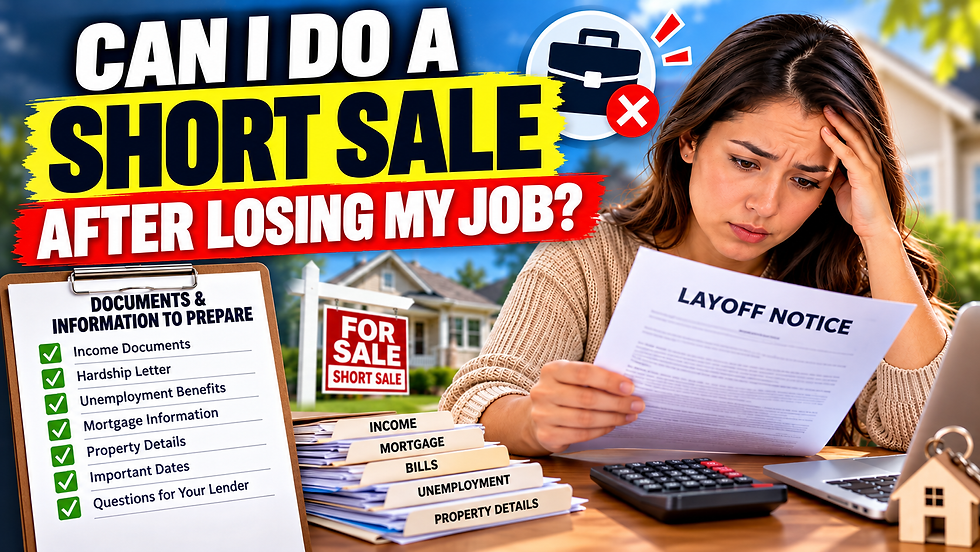
If you have lost your job and are struggling to make your mortgage payments, preparing your financial documents, hardship explanation, important dates, income information, and questions for your mortgage servicer is an important first step. Job loss can be considered a financial hardship, but it does not automatically qualify a homeowner for a short sale. The available options depend on the mortgage, financial circumstances, property, servicer, and applicable requirements. The Consumer Financial Protection Bureau recommends contacting your mortgage servicer promptly if you are worried about making your payments.
This short sale after job loss checklist explains what to prepare before taking the next step.
What Should a Homeowner Prepare Before Taking the Next Step?
Before discussing a short sale, organize five areas of information:
Income and job-loss information
Mortgage and property documents
Hardship explanation
Important dates and deadlines
Questions for your mortgage servicer and other professionals
Having this information organized can make it easier to explain what changed financially and respond to requests for additional documentation.
1. Start With Your Job Loss and Income Documentation
The first part of a short sale after job loss checklist is documenting exactly what happened to your income.
The CFPB identifies unemployment as an example of a hardship that can significantly reduce income or increase financial pressure. A loss-mitigation application generally requires the borrower to explain the hardship and provide supporting evidence.
Gather These Documents
Depending on what your servicer requests, collect:
Employment termination or layoff notice
Final pay stub
Recent pay stubs from before the job loss
Employment separation documentation
Severance information
Unemployment benefit approval
Unemployment payment records
Documentation of any temporary employment
Documentation of other current income
Recent tax returns, if requested
If you have already found another job, include documentation of the new income as appropriate.
Why This Information Matters
Your mortgage servicer needs to understand the difference between your previous financial situation and your current one.
For example:
Before job loss:Monthly employment income → regular mortgage payment → manageable expenses
After job loss:Reduced income → unemployment or temporary income → mortgage payment becomes difficult to maintain
Keeping the documentation organized helps establish a clear timeline.
2. Prepare a Clear Hardship Letter
A hardship letter is another important part of preparing for a mortgage review.
The CFPB explains that many loss-mitigation applications require borrowers to describe the change in financial circumstances preventing them from paying their mortgage. Supporting evidence may also be required.
What Should a Job-Loss Hardship Letter Include?
Your hardship letter should answer several straightforward questions.
What happened?
Explain that you lost your job and provide the date or approximate date the employment ended.
How did your income change?
Explain how your household income changed after the job loss.
Why is the mortgage difficult to maintain?
Connect the income reduction to your mortgage payment and other necessary expenses.
What is your current situation?
Explain whether you are:
Receiving unemployment benefits
Searching for employment
Working temporarily
Using savings
Receiving severance
Receiving other income
What are you asking the servicer to review?
If you are considering a short sale, explain that you want to discuss whether a short sale or another loss-mitigation option may be available.
Keep the letter factual and consistent with the financial documents you submit.
3. Gather Your Mortgage and Property Information
Before discussing a short sale, make sure you understand the basic information about your mortgage and property.
Mortgage Documents to Locate
Gather:
Current mortgage statement
Loan number
Mortgage servicer's contact information
Approximate outstanding loan balance
Monthly payment
Interest rate
Information about escrow
Recent correspondence from the servicer
Any previous loss-mitigation documents
Also determine whether there are other loans or liens connected to the property.
Property Information to Gather
You may also want to organize:
Property address
Recent property tax information
Homeowners association information, if applicable
Information about other liens
Recent appraisal or valuation information, if available
Estimated current market value
Information about necessary repairs
A short sale generally involves selling a property for less than the amount owed on the mortgage, subject to the required approval.
4. Create a Complete Monthly Financial Picture
A lender or servicer needs more than information about your job loss.
You should also understand your current financial position.
Create a simple worksheet containing:
Category | Information to Prepare |
Employment income | Current monthly income |
Unemployment | Benefit amount and payment schedule |
Other income | Any additional current income |
Mortgage | Monthly payment and balance |
Utilities | Average monthly costs |
Insurance | Monthly or annual costs |
Property taxes | Current obligation |
Transportation | Vehicle payments and related costs |
Credit cards | Minimum monthly payments |
Other debts | Loans and recurring obligations |
Cash | Current bank balances |
Assets | Savings and other significant assets |
This does not determine whether you qualify for a short sale. Instead, it helps you accurately explain your financial circumstances.
The CFPB specifically advises borrowers who are having mortgage-payment problems to be prepared to discuss income, expenses, and other assets when contacting their servicer.
5. Document Your Unemployment Benefits
Unemployment benefits can be an important part of your financial picture after losing a job.
The CFPB recommends filing for unemployment after an unexpected job loss and notes that unemployment benefits generally replace only part of previous employment income.
Keep Copies of:
Benefit approval letter
Weekly or biweekly benefit amount
Payment history
Benefit expiration information
Correspondence regarding your claim
Documentation of any appeal or change in benefits
Important: Do Not Assume How Benefits Will Be Counted
The treatment of unemployment benefits can vary by mortgage program and investor requirements.
For example, different loan programs can have specific rules governing income calculations and short-sale eligibility.
Provide accurate information and ask your servicer how unemployment benefits will be treated under your particular loan.
6. Make a List of Important Dates
Timing can matter when you are dealing with mortgage difficulty.
Create a simple timeline that includes:
Employment Dates
Last day worked
Date employment ended
Date unemployment benefits began
Expected benefit expiration date, if known
New employment start date, if applicable
Mortgage Dates
Next mortgage payment due date
Date of any missed payment
Date of any previous missed payment
Date of servicer correspondence
Any deadline listed in a mortgage notice
Foreclosure-Related Dates
If you have received legal or foreclosure-related documents, record every deadline.
Do not assume that an internet article gives you the deadline applicable to your specific situation.
The CFPB explains that foreclosure and loss-mitigation timelines can involve important deadlines, including requirements relating to complete applications and scheduled foreclosure sales.
7. Prepare Questions Before Calling Your Mortgage Servicer
A phone call with your servicer can involve a lot of information.
Write your questions down beforehand.
Questions About Your Hardship
Does job loss qualify as a hardship under my loan?
What documentation do you need?
Do you require a hardship letter?
What financial forms must I complete?
Questions About a Short Sale
Is a short sale an available option for my loan?
What are the eligibility requirements?
What documents are required?
Does the property need a valuation or appraisal?
What happens after an offer is submitted?
How long does the review typically take?
Questions About Other Options
Is forbearance available?
Is a repayment plan available?
Is a loan modification available?
Is a deed-in-lieu of foreclosure available?
What other loss-mitigation options should I consider?
The CFPB lists several potential options for homeowners struggling with mortgage payments, including loan modification, repayment plans, forbearance, short sale, and deed-in-lieu of foreclosure.
8. Identify the Right People to Contact
You do not have to figure everything out alone.
Depending on your situation, you may need to communicate with several people.
Mortgage Servicer
Your servicer should be your starting point for understanding available loss-mitigation options and required documentation.
Real Estate Professional
If a short sale is being considered, a real estate professional experienced with short-sale transactions may help you understand the property-sale side of the process.
HUD-Approved Housing Counselor
HUD-approved housing counselors provide independent assistance with mortgage delinquency, foreclosure prevention, budgeting, and related housing concerns.
Attorney or Tax Professional
Depending on the circumstances, you may also want professional advice about legal or tax consequences.
This is especially important when reviewing documents concerning a potential remaining balance, deficiency, or other financial obligation.
9. Understand What a Short Sale Actually Means
Before taking the next step, make sure you understand what a short sale is.
The CFPB defines a short sale as a sale of the home for less than what is owed on the mortgage. The lender or servicer must agree to the transaction.
A short sale is not simply putting the property on the market and accepting any offer.
The transaction may require review and approval from the appropriate parties.
Federal mortgage-servicing rules describe an approved short sale as a transaction approved by all relevant parties, which may include the servicer and other affected lienholders or insurers, depending on the circumstances.
10. Ask About Any Remaining Mortgage Balance
This is one of the most important questions to ask before completing a short sale.
If the home sells for less than the mortgage balance, ask:
Will the remaining deficiency be waived?
The answer depends on the loan, approval terms, applicable law, and other circumstances.
The CFPB specifically advises homeowners to ask the lender to waive a deficiency where applicable and to obtain any waiver in writing.
Do not assume that completing a short sale automatically eliminates every possible obligation.
Review the final approval documents carefully before proceeding.
Your Short Sale After Job Loss Checklist
Use this condensed checklist to prepare for your conversation with the mortgage servicer.
Income and Employment
☐ Employment termination or layoff documentation
☐ Final pay stub
☐ Recent pay stubs
☐ Unemployment benefit documentation
☐ Severance information
☐ New employment information, if applicable
☐ Other income documentation
Mortgage
☐ Current mortgage statement
☐ Loan number
☐ Mortgage balance
☐ Monthly payment
☐ Servicer contact information
☐ Recent mortgage correspondence
Financial Information
☐ Recent bank statements
☐ Monthly expenses
☐ Credit card payments
☐ Other debt information
☐ Savings information
☐ Asset information
Property
☐ Property address
☐ Estimated market value
☐ Property tax information
☐ HOA information, if applicable
☐ Other lien information
☐ Repair information
Hardship
☐ Hardship letter
☐ Date hardship began
☐ Explanation of income loss
☐ Current financial situation
☐ Requested assistance
Timing
☐ Next mortgage payment date
☐ Missed-payment dates, if any
☐ Servicer deadlines
☐ Foreclosure-related deadlines, if applicable
☐ Unemployment benefit dates
Questions
☐ Is a short sale available?
☐ What documents are required?
☐ How will unemployment benefits be treated?
☐ What other options are available?
☐ What happens after submitting the application?
☐ What happens to any remaining balance?
☐ Are there other lienholders?
☐ What deadlines apply?
What Should You Do After Preparing the Checklist?
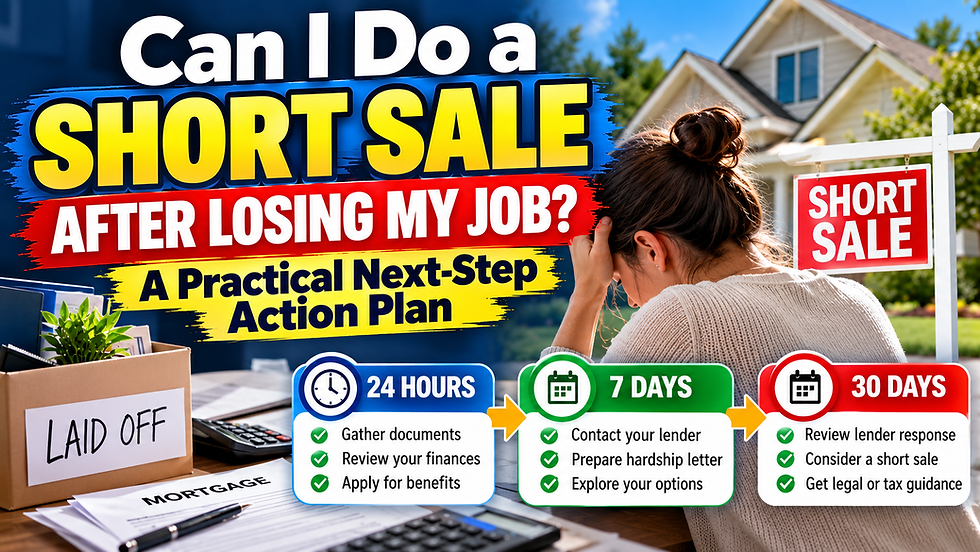
Once your documents are organized, contact your mortgage servicer.
The CFPB recommends contacting the servicer as soon as you know you may have trouble making your mortgage payment.
During the conversation, explain:
“I recently lost my job and my income has changed. I want to understand what mortgage assistance and loss-mitigation options may be available, including whether a short sale should be considered.”
Then ask for the specific application and document requirements for your loan.
Keep a record of:
Date of the call
Representative's name or identification number
Case or reference number
Documents requested
Submission method
Deadlines
Follow-up date
Being organized can make it easier to track the process and respond when additional information is requested.
Frequently Asked Questions About a Short Sale After Job Loss Checklist
1. What should a homeowner prepare before taking the next step?
Prepare documentation showing your job loss, current income, unemployment benefits, mortgage obligations, expenses, assets, property information, hardship circumstances, and important deadlines. Also prepare a list of questions for your mortgage servicer.
2. Can job loss qualify as a mortgage hardship?
Yes. The CFPB identifies unemployment as an example of a hardship that can significantly reduce income or increase expenses. However, a hardship does not automatically qualify someone for a particular loss-mitigation option.
3. What documents are needed for a short sale after job loss?
Requirements vary, but you may need a mortgage statement, bank statements, employment-loss documentation, unemployment benefit information, income and expense records, asset information, a hardship letter, and other documents requested by your servicer.
4. Should I include unemployment benefits in my documentation?
Yes. You should provide accurate information about your current income and benefits when completing a mortgage assistance or loss-mitigation review. How unemployment benefits are treated can depend on the specific loan and applicable requirements.
5. Do I need to wait until I miss a mortgage payment?
No. You should not assume that you need to wait. The CFPB recommends contacting your mortgage servicer as soon as you know you may have trouble making your mortgage payment.
6. Does losing my job automatically qualify me for a short sale?
No. Job loss can be a hardship, but short-sale eligibility depends on the specific circumstances and requirements of the mortgage. Property value, mortgage balance, documentation, the proposed transaction, and other factors can also matter.
7. Who can help me understand my options?
Your mortgage servicer can explain the loss-mitigation options available for your loan. A HUD-approved housing counselor can also provide independent assistance with mortgage delinquency and foreclosure-prevention issues.
Final Takeaway: Prepare Before You Take the Next Step
If you have lost your job and are considering a short sale, do not start with the assumption that you need to sell immediately. Start by understanding your financial situation and preparing the right information.
The most important items are your job-loss documentation, hardship letter, income and unemployment information, mortgage records, financial statements, property information, important dates, and questions for your servicer.
A short sale is one potential loss-mitigation option, not an automatic outcome. The CFPB recommends contacting your mortgage servicer promptly when you are concerned about making your payments, while HUD-approved housing counselors can provide additional assistance.
Talk Through Your Hardship and Timeline
Talk through your hardship and timeline before making assumptions about your next move. Having your documents and questions ready can help you have a clearer conversation about the options available for your specific situation.
This article is for general educational purposes only and is not legal, tax, financial, or mortgage-servicing advice. Short-sale requirements, timelines, and consequences can vary based on the mortgage, investor, servicer, property, and applicable law. No outcome is guaranteed. Consider consulting your mortgage servicer, a HUD-approved housing counselor, and qualified legal or tax professionals when appropriate.


Comments