Who Qualifies for a Short Sale? Common Requirements and Hardships: A Practical Next-Step Action Plan

If you are considering a short sale, the next step is to gather your mortgage, property, income, expense, asset, and hardship information and contact your mortgage servicer to understand your available options. A short sale may be considered when a home's value is less than the mortgage debt and the homeowner has circumstances that make the mortgage difficult to maintain. However, qualification and approval are case-specific. The Consumer Financial Protection Bureau (CFPB) recommends contacting the mortgage servicer promptly when you are struggling with mortgage payments and being prepared to explain your income, expenses, assets, and financial circumstances.
What Is a Short Sale?
A short sale is a sale of a home for less than the amount owed on the mortgage, with the lender or mortgage servicer agreeing to the transaction. It is one potential alternative to foreclosure for homeowners experiencing mortgage difficulties.
For example, a homeowner might owe $350,000 on a mortgage while the property may currently be worth approximately $290,000. That difference can create negative equity.
But negative equity alone does not automatically mean a homeowner qualifies.
The lender or servicer may review the homeowner's financial hardship, property value, loan information, documentation, proposed sale, and other circumstances before deciding whether to approve a short sale.
That is why understanding your short sale qualifications next steps is important before making assumptions about the outcome.
Who May Qualify for a Short Sale?
There is no single universal qualification checklist that guarantees approval.
A homeowner may be considered for a short sale when several circumstances exist, such as:
The property may be worth less than the mortgage balance.
The homeowner is experiencing a documented financial hardship.
Maintaining the mortgage has become difficult or unsustainable.
The homeowner can provide requested financial documentation.
The proposed sale does not generate enough proceeds to fully satisfy the mortgage.
The mortgage servicer or lender is willing to review and potentially approve the transaction.
The CFPB explains that a short sale requires the lender or servicer's agreement and may be an option when a homeowner owes more than the home is worth.
Because every loan and financial situation is different, homeowners should treat these as common factors to investigate, not automatic qualification rules.
Your Short Sale Qualifications Next Steps
A calm, organized approach can make it easier to understand your situation.
Think about the process in three stages:
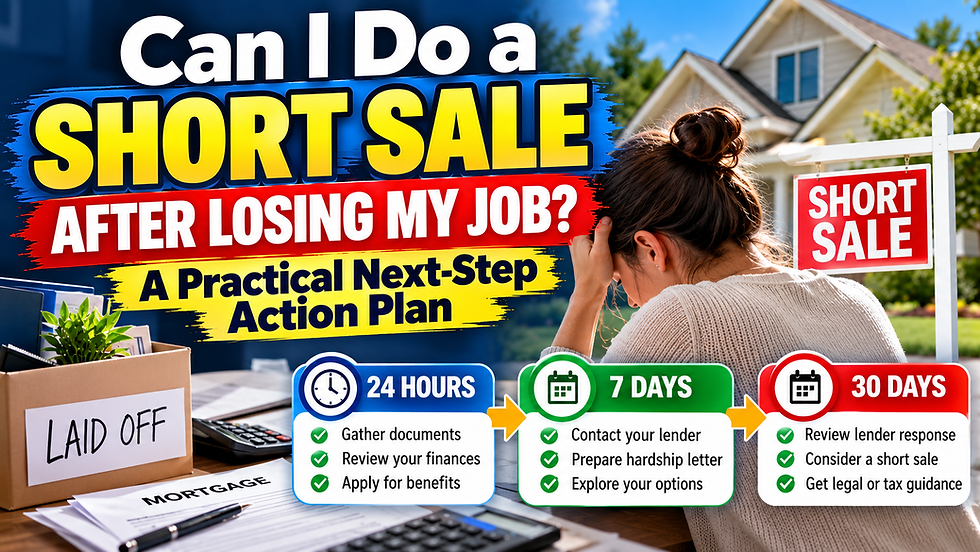
Next 24 hours → Gather the factsNext 7 days → Start the reviewNext 30 days → Evaluate the available path
The timeline can vary depending on your circumstances, lender requirements, and any foreclosure-related deadlines.
The Next 24 Hours: Gather the Basic Facts
Your first goal is not to solve everything.
Your goal is to understand your starting position.
1. Find Your Current Mortgage Balance
Locate your most recent mortgage statement.
Write down:
Current loan balance
Monthly payment
Loan number
Mortgage servicer
Payment status
Past-due amount, if applicable
Contact information for the servicer
If you have more than one mortgage or loan secured by the property, identify each one.
Multiple liens can make the process more complicated because other lienholders may also need to approve aspects of the transaction.
2. Estimate Your Current Property Value
Next, get a reasonable estimate of what the property may be worth today.
Consider:
Recent comparable sales
Current listings
Property condition
Major repairs needed
Recent appraisal or valuation information
Local market information
Do not assume that an online estimate is the same as the valuation used by a lender or servicer.
The purpose at this stage is simply to determine whether there may be a significant difference between your estimated property value and mortgage debt.
3. Write Down What Changed Financially
Ask yourself:
What changed that made the mortgage harder to maintain?
Possible circumstances may include:
Job loss
Reduced income
Reduced working hours
Major unexpected expenses
Medical expenses
Divorce or separation
Death of an income contributor
Relocation
Business income changes
Other significant financial changes
Write down what happened and when it happened.
A simple timeline can make it easier to explain your circumstances accurately.
4. Gather Your Most Important Documents
Start collecting:
Mortgage statements
Recent pay stubs
Bank statements
Tax documents
Income records
Monthly expense information
Asset information
Hardship documentation
Lender correspondence
Do not worry if you do not have everything immediately.
The objective for the first 24 hours is to create an organized starting point.
The Next 7 Days: Start the Lender and Professional Review
Once you understand your basic numbers, the next stage is communication and documentation.
1. Contact Your Mortgage Servicer
If you are struggling with your mortgage or are concerned about missing payments, contact your servicer promptly.
The CFPB recommends being prepared to explain:
Why you are having difficulty making payments
Whether the problem is temporary or permanent
Your income
Your expenses
Your assets
Other relevant financial circumstances
Ask specifically what loss-mitigation options may be available.
A short sale is only one possible option. Depending on the circumstances, a servicer may also discuss options such as loan modification, repayment arrangements, forbearance, or a deed-in-lieu of foreclosure.
2. Ask What Documents Are Required
Do not rely on a generic online checklist as your only source.
Ask the servicer:
What documents do you require?
Where should documents be submitted?
What forms need to be completed?
How should income be documented?
What hardship documentation is required?
Are there deadlines?
Are there additional loans or liens that must be addressed?
Requirements can vary by loan and servicer.
3. Organize Your Financial Information
Create one folder—digital or physical—for your short-sale documents.
Separate it into:
Mortgage
Statements
Loan information
Lender correspondence
Income
Pay stubs
Tax returns
W-2s
Business income records
Expenses
Housing costs
Utilities
Transportation
Medical expenses
Other recurring obligations
Assets
Bank accounts
Investments
Retirement accounts
Other significant assets
Hardship
Employment changes
Income changes
Major expenses
Other supporting documentation
Keeping everything together can make it easier to respond when additional information is requested.
4. Consider a HUD-Approved Housing Counselor
A HUD-approved housing counseling agency can help homeowners understand available mortgage-assistance and foreclosure-avoidance options.
The CFPB notes that HUD-approved housing counselors can provide assistance at no cost and can help homeowners evaluate available options.
This can be particularly useful if you are uncertain whether a short sale is the appropriate option to investigate.
The Next 30 Days: Evaluate the
Available Path
The first month should focus on understanding your options rather than assuming a particular outcome.
1. Review Your Property and Mortgage Position
By this point, try to have a clearer picture of:
Mortgage balance
Estimated property value
Potential equity or negative equity
Monthly payment
Payment status
Other liens
Estimated selling costs
Financial hardship
Current income and expenses
This information can help frame the conversation with the servicer and real estate professionals involved.
2. Understand the Short-Sale Approval Process
A buyer's offer does not necessarily mean a short sale has been approved.
The lender or servicer may need to review the transaction before it can proceed.
Depending on the circumstances, the review can involve:
Property information
Valuation
Purchase offer
Mortgage balance
Financial information
Hardship documentation
Closing costs
Other liens
Required approvals
The CFPB states that a short sale requires approval from the mortgage servicer, and other mortgage servicers may also need to approve a transaction when additional mortgages exist.
3. Ask About Any Remaining Debt
This is one of the most important short sale qualifications next steps.
If the home sells for less than the mortgage balance, there may be a difference between the sale proceeds and the amount owed.
Ask:
Will the lender waive any remaining deficiency?
The CFPB advises homeowners to ask the lender to waive a deficiency when applicable and to obtain the waiver in writing if one is provided.
Do not assume that a short sale automatically eliminates every potential obligation.
Questions about personal liability for remaining debt can require legal guidance.
4. Review Potential Tax Consequences
Canceled or forgiven debt can have tax consequences.
The IRS generally states that canceled debt may be taxable income, although exceptions and exclusions can apply depending on the circumstances.
Because tax treatment can depend on the type of debt, the property, the timing, and the homeowner's individual circumstances, a qualified tax professional should review specific questions.
Do not rely on a general online article to determine your individual tax liability.
5. Watch Every Deadline
If you have received foreclosure notices or other legal documents, do not ignore them.
Keep track of:
Mortgage payment deadlines
Lender response deadlines
Document submission deadlines
Scheduled foreclosure dates
Listing deadlines
Contract deadlines
Legal deadlines
The CFPB notes that if foreclosure is imminent or a homeowner has been served with legal papers, consulting an attorney may be appropriate.
What Should a Homeowner Do Next?
The most practical answer is:
Gather your mortgage and financial information, document your hardship, estimate your property's current value, contact your mortgage servicer, and ask what short-sale or other loss-mitigation options may be available.
Do not wait until every document is perfect before communicating with the servicer if you are already struggling with payments.
At the same time, avoid making major decisions based on assumptions about qualification, debt forgiveness, taxes, or foreclosure timing.
Your circumstances should be reviewed based on the actual numbers and documents.
A Simple 24-Hour, 7-Day and 30-Day Checklist
Within 24 Hours
Locate your latest mortgage statement
Write down your mortgage balance
Identify your mortgage servicer
Estimate your home's current value
Identify other mortgages or liens
Write down when your financial hardship began
Gather recent income and bank documents
Identify important payment or foreclosure dates
Within 7 Days
Contact your mortgage servicer
Ask about short-sale requirements
Ask about other loss-mitigation options
Request a list of required documents
Organize your financial records
Document your hardship
Consider contacting a HUD-approved housing counselor
Identify questions requiring legal or tax advice
Within 30 Days
Review your property value and mortgage balance
Understand the lender's review process
Address additional liens
Discuss potential deficiency liability
Review potential tax consequences
Monitor all lender communications
Track every deadline
Compare available options based on your circumstances
Why Short Sale Approval Is Case-Specific
One of the most important things to understand is that there is no universal formula for short-sale approval.
Two homeowners can have similar mortgage balances and property values but receive different outcomes because their financial circumstances, loan structures, documentation, liens, or lender requirements differ.
Negative equity may be relevant.
Financial hardship may be relevant.
Complete documentation may be important.
But none of these factors alone guarantees approval.
The CFPB describes a short sale as an option that requires the lender or servicer's agreement, reinforcing why the lender review is an essential part of the process.
Frequently Asked Questions About Short Sale Next Steps
1. What should I do first if I think I need a short sale?
Start by gathering your mortgage balance, property-value information, income, expenses, assets, hardship information, and important deadlines. Then contact your mortgage servicer to ask about available options.
2. Do I need to stop making mortgage payments before considering a short sale?
Do not assume that you should stop making payments. The CFPB advises homeowners experiencing mortgage difficulty to contact their servicer promptly and discuss available options.
3. How do I know if I have negative equity?
Compare your current mortgage debt with a reasonable estimate of your property's current market value. A lender may use its own valuation during a short-sale review.
4. Does financial hardship guarantee short-sale approval?
No. Financial hardship can be an important consideration, but approval depends on the complete circumstances and lender or servicer requirements.
5. What happens if there is a second mortgage?
Additional mortgage servicers or lienholders may need to approve the transaction. Identify all liens early rather than discovering them late in the process.
6. Could a short sale affect my taxes?
Potentially. The IRS states that canceled debt may generally be taxable unless an exception or exclusion applies. The tax treatment depends on the specific circumstances, so professional tax advice may be appropriate.
7. Should I talk to an attorney?
Legal guidance may be appropriate if you have questions about deficiency liability, legal notices, foreclosure proceedings, contracts, or the terms of a short-sale approval. The CFPB specifically recommends considering an attorney when foreclosure is imminent or legal papers have been served.
Check Your Likely Eligibility
If you are researching short sale qualifications next steps, you do not have to figure out every part of the process at once.
Start with the facts:
What is the home worth?How much is owed?What financial hardship occurred?What documentation is available?What deadlines are approaching?What does the mortgage servicer require?
Organizing this information can help you better understand whether a short sale should be explored and what questions to ask next.
Check Your Likely Eligibility
Check your likely eligibility by reviewing your mortgage position, property value, financial hardship, income, expenses, assets, and loan information.
A review does not guarantee short-sale approval. It is a practical starting point for understanding your circumstances and discussing available options.
This article is for general educational purposes only and is not legal, tax, financial, mortgage-servicing, or lender-specific advice. Short-sale requirements and outcomes vary by loan, lender, servicer, property, and individual circumstances. Consult the appropriate qualified professional regarding your situation.


Comments